
Omdia: Global Smartphone Shipments Fell 20% in 3Q26, the Lowest Third-quarter Total Since 2013
LONDON–(BUSINESS WIRE)–
Global smartphone shipments fell 20% year-on-year (YoY) to 254.7 million units in 3Q26, according to Omdia, marking the lowest third-quarter shipment volume since 2013. Rising smartphone prices continued to weigh on consumer demand, particularly in emerging markets. Distributors and retailers also remained cautious about replenishing inventory ahead of the holiday season, as higher device costs increased working capital requirements and limited stocking volumes.
This press release features multimedia. View the full release here: https://www.businesswire.com/news/home/20261029800342/en/
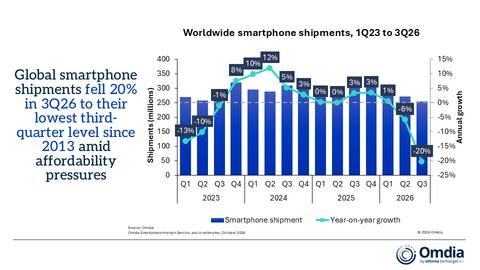
Worldwide smartphone shipments, 1Q23 to 3Q26
Vendor Highlights
Samsung retained its position as the world’s largest smartphone vendor, shipping 57.8 million units, down 5% YoY. Its entry- and mid-range Galaxy A series helped it remain competitive as rival Android brands faced memory supply constraints and higher price. This supported Samsung’s shipment volumes and global market leadership. Meanwhile, the August launch of the Galaxy Z8 series, supported by trade-in and upgrade programs, strengthened its position in the premium segment.
Apple shipped 56.5 million iPhones in 3Q26, remaining flat YoY despite the global market downturn. Resilient demand in China and North America offset weakness in key emerging markets, supported by sustained iPhone 17 demand and advance channel stocking ahead of anticipated price increases. In September, Apple introduced the iPhone 18 Pro, iPhone 18 Pro Max and its first foldable model, the iPhone Duo, while deferring the base iPhone 18 to 2027. This strategy extends the iPhone 17’s sales cycle while concentrating new-product demand on premium devices for the holiday season.
Xiaomi retained third place with 30.7 million units shipped, down 29% YoY, as shipments declined 20% in China and 28% in India. Amid rising component costs, Xiaomi continued to adjust prices across markets, prioritizing margin protection, with a more pronounced impact on volume in price-sensitive emerging markets. The Redmi A7 Pro and Redmi 17 helped support shipments but were insufficient to offset the broader decline.
OPPO (including realme and OnePlus) ranked fourth with 23.4 million units shipped, down 39% YoY, while vivo ranked fifth with 19.3 million units, down 33% YoY. Both vendors continued to raise prices across their core markets in response to rising component costs, making channel inventory planning more challenging.
Market Dynamics: Emerging markets face the sharpest downturn as affordability pressures intensify
“Emerging markets, once the backbone of global smartphone volume growth, are now facing the greatest pressure from rising prices,” said Sanyam Chaurasia, Principal Analyst at Omdia. “Africa recorded the steepest contraction at 39% YoY, as rising costs shifted vendors’ focus from aggressive expansion and market share gains toward margin protection and selective shipments, despite underlying demand. APAC excluding Greater China, the Middle East and Latin America also declined by over 20%. Currency depreciation, inflation, and rising living costs further weakened purchasing power, prompting consumers to delay upgrades or switch to refurbished smartphones and, in some lower-income markets, forcing them to opt for feature phones. In contrast, North America remained relatively resilient, supported by its premium-heavy market and established operator financing, trade-in and upgrade programs.”
Major mass-market smartphone vendors are increasingly prioritizing profitable markets and core product portfolios as component supply remains constrained. To remain competitive, they are adjusting RAM and storage configurations, reducing SKUs and selectively absorbing higher costs, while expanding higher-value portfolios to protect profitability.
Market Outlook: Rising costs and inventory pressures weigh on smartphone demand in 2026–27
“Omdia expects global smartphone shipments to decline by 12% in 2026, with further price increases and limited room for promotional discounts expected to weigh on demand during the holiday season,” said Amber Liu, Practice Leader at Omdia. “Beyond rising component costs, vendors face growing inventory risks as they balance existing stock with new product generations. Telecom operators and large-format retailers are better positioned to manage higher device prices and working capital requirements. Meanwhile, independent retailers face mounting pressure from slower inventory turnover and shrinking margins, potentially accelerating market exits.”
The global smartphone market is expected to decline further in 2027, albeit at a slower pace. Persistent high-bandwidth memory (HBM) shortages and constraints on conventional memory supply are expected to keep costs elevated, limiting relief for smartphone vendors. Vendors are expected to optimize sales, retail and marketing costs while pursuing additional revenue through software, services and post-sale offerings. Strong balance sheets, lean inventories and operational efficiency will become key competitive differentiators for vendors and channel partners.
|
Global smartphone shipments and annual growth |
|
||||
|
Vendor |
3Q26 |
3Q25 |
Annual Growth |
||
|
Shipment (Million) |
Market Share |
Shipment (Million) |
Market Share |
||
|
Samsung |
57.8 |
23% |
60.6 |
19% |
-5% |
|
Apple |
56.5 |
22% |
56.5 |
18% |
0% |
|
Xiaomi |
30.7 |
12% |
43.4 |
14% |
-29% |
|
OPPO |
23.4 |
9% |
38.4 |
12% |
-39% |
|
vivo |
19.3 |
8% |
28.5 |
9% |
-33% |
|
Others |
67.0 |
26% |
92.5 |
29% |
-28% |
|
Total |
254.7 |
100% |
320.1 |
100% |
-20% |
|
Notes: OPPO includes OnePlus and realme. Xiaomi includes sub-brands Redmi and POCO. Percentages may not add up to 100% due to rounding. |
|||||
|
Source: Omdia |
|
|
|
© 2026 Omdia |
|
About Omdia
Omdia, part of TechTarget, Inc. d/b/a Informa TechTarget (Nasdaq: TTGT), is a technology research and advisory group. Our deep knowledge of tech markets grounded in real conversations with industry leaders and hundreds of thousands of data points, make our market intelligence our clients’ strategic advantage. From R&D to ROI, we identify the greatest opportunities and move the industry forward.
View source version on businesswire.com: https://www.businesswire.com/news/home/20261029800342/en/
Fasiha Khan: [email protected]
Eric Thoo: [email protected]
KEYWORDS: Europe United Kingdom Asia Pacific
INDUSTRY KEYWORDS: Consumer Electronics Retail Other Retail Technology Telecommunications Mobile/Wireless Hardware
MEDIA:
| Photo |
 |
| Worldwide smartphone shipments, 1Q23 to 3Q26 |
| Photo |
 |
| Worldwide smartphone shipment market share, top vendors, 1Q23 to 3Q26 |
| Photo |
 |
| Worldwide smartphone estimates by region, 3Q 2025 and 3Q 2026 |
| Logo |
 |