
Omdia: Middle East Smartphone Shipments Fall 29% in 3Q26, Marking the Sharpest Decline in Two Years
LONDON–(BUSINESS WIRE)–
Smartphone shipments in the Middle East (excluding Turkey) fell 29% year-on-year (YoY) to 10.7 million units in 3Q26, according to Omdia’s latest research. Rising component costs, limited availability of entry-level devices and weaker retail demand drove the decline. Seasonal softness during summer travel, geopolitical uncertainty and cautious channel replenishment added further pressure. As prices continued to rise, vendors focused on managing inventory and allocating support selectively, particularly in lower-priced smartphone segments.
This press release features multimedia. View the full release here: https://www.businesswire.com/news/home/20261116715868/en/
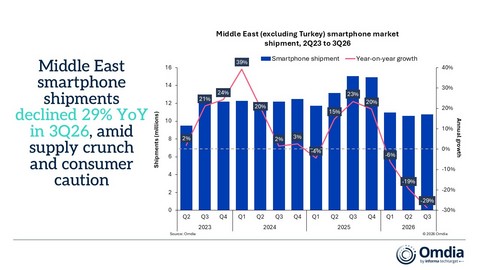
Middle East (excluding Turkey) smartphone market shipment, 2Q23 to 3Q26
The downturn was uneven across the region. Shipments in Saudi Arabia declined 29% and those in the UAE fell 12%, with retailers reporting fewer store visits during the extended summer travel season despite back-to-school promotions and National Day offers. In Iraq, shipments fell 58% YoY to their lowest quarterly level since 1Q23. Currency pressures, political and economic instability, and climbing smartphone prices made devices less affordable in this price-sensitive market. Elsewhere in the region, macroeconomic challenges added to vendors’ operational pressures.
“The Middle East smartphone market is becoming more expensive, although this does not necessarily reflect a shift in consumer preferences toward premium devices,” said Manish Pravinkumar, Principal Analyst at Omdia. “As rising component costs squeeze entry-level profitability, vendors are scaling back lower-priced models and prioritizing higher-margin devices. This has contributed to a 56% contraction in sub-$200 shipments, while shipments in the $400–599 segment expanded 65%, pushing the regional average selling prices to a record $511. The changing mix of available devices is contributing to this increase, with many price-sensitive buyers extending replacement cycles as affordable choices narrow.”
- Samsung increased its market share to 45%, up from 34% a year earlier, supported by strong demand for the Galaxy A17 and A07 4G and stable component supply. Its broad portfolio across price tiers helped limit its shipment decline as consumers became increasingly price conscious.
- Xiaomi returned to second position, driven by the Redmi 17 4G and Redmi A7 Pro 4G. The company continued to scale back its focus on entry-level devices, prioritizing higher-margin models and markets.
- Apple increased its market share to 12% despite declining shipments, supported by premium demand and established channel partnerships. The absence of a base iPhone 18 at launch resulted in lower shipments to the channel compared with the broader iPhone 17 lineup a year earlier.
- HONOR recorded its first double-digit shipment decline after three years of consecutive growth, despite expanding its offering in the sub $150 segment with the HONOR Choice T10. The HONOR X7e accounted for approximately one-fifth of the vendor’s shipments, highlighting the continued importance of its higher-priced X-series models.
- TRANSSION recorded the sharpest contraction among the top five vendors, as rising component costs put pressure on its low-price strategy. TECNO became its largest brand by shipments, led by models such as the Spark Go 3. Iraq and Saudi Arabia remained important markets for the group despite weaker demand.
Looking ahead, markets across the region are expected to follow different trajectories. Vendors in Saudi Arabia are likely to rely more on financing and tighter inventory management to sustain replacement demand. The UAE is projected to remain comparatively resilient, supported by premium smartphone demand, trade-in programmes, and its established retail ecosystem. Iraq faces a more prolonged adjustment, with consumers replacing devices less frequently and becoming more selective about purchases, while vendors streamline their entry-level portfolios. These differences are likely to persist as vendors adapt their strategies to local affordability conditions.
“After a challenging 2026, the Middle East smartphone market is forecast to record a single-digit decline in 2027,” concluded Pravinkumar. “Consumers are becoming more cautious about spending as geopolitical uncertainty and rising component costs affect purchasing decisions. Financing options and trade-in values are playing a greater role in upgrade decisions alongside brand preferences. In the near term, vendors and retailers are projected to focus on leaner inventories, tighter working capital management and selective model launches to protect profitability amid elevated component costs. Over the longer term, vendors are expected to place greater emphasis on sustainable returns, streamline operating and marketing expenses, and strengthen channel support and partnerships.”
|
Middle East* smartphone shipment and annual growth |
|||||
|
Omdia Smartphone Market Pulse: 3Q26 |
|||||
|
Vendor |
3Q26 |
3Q26 |
3Q25 |
3Q25 |
Annual |
|
shipments |
market |
shipments |
market |
growth |
|
|
(million) |
share |
(million) |
share |
|
|
|
Samsung |
4.8 |
45% |
5.2 |
34% |
-6% |
|
Xiaomi |
1.3 |
12% |
2.3 |
15% |
-42% |
|
Apple |
1.3 |
12% |
1.4 |
9% |
-8% |
|
HONOR |
1.1 |
11% |
1.6 |
10% |
-27% |
|
TRANSSION |
0.9 |
9% |
2.7 |
18% |
-66% |
|
Others |
1.2 |
11% |
1.9 |
13% |
-38% |
|
Total |
10.7 |
100% |
15.1 |
100% |
-29% |
|
|
|||||
|
Note: Xiaomi includes Redmi and POCO, TRANSSION includes TECNO, Infinix and iTel |
|
||||
|
Percentages may not add up to 100% due to rounding. |
|||||
|
*Excluding Turkey |
|||||
|
Source: Omdia Smartphone Horizon Service (sell-in shipments), November 2026 |
|||||
ABOUT OMDIA
Omdia, part of TechTarget, Inc. d/b/a Informa TechTarget (Nasdaq: TTGT), is a technology research and advisory group. Our deep knowledge of tech markets, grounded in real conversations with industry leaders and hundreds of thousands of data points, makes our market intelligence our clients’ strategic advantage. From R&D to ROI, we identify the greatest opportunities and move the industry forward.
View source version on businesswire.com: https://www.businesswire.com/news/home/20261116715868/en/
Fasiha Khan: [email protected]
Eric Thoo: [email protected]
KEYWORDS: United States United Kingdom North America Asia Pacific Middle East Europe
INDUSTRY KEYWORDS: Other Retail Internet Consumer Electronics Wearables/Mobile Technology Technology Mobile/Wireless Retail Other Technology
MEDIA:
| Photo |
 |
| Middle East (excluding Turkey) smartphone market shipment, 2Q23 to 3Q26 |
| Photo |
 |
| Smartphone shipments by price band, Middle East (excluding Turkey), 1Q24 to 3Q26 |
| Photo |
 |
| Middle East (excluding Turkey) smartphone shipment market share, top vendors, 2Q24 to 3Q26 |
| Logo |
 |